

Hosted SaaS solution for AS2 and SFTP file transfer. No infrastructure, instant setup.
Start Free Trial
ViDA makes EN 16931 e-invoicing mandatory for intra-EU B2B from 1 July 2030. Learn why one AS4 and Peppol architecture beats country-by-country rebuilds.
Harindu Fernando
Published: 07 Oct 2026
VAT in the Digital Age (ViDA) is usually filed under tax. It should sit on the integration team’s desk instead. From 1 July 2030, structured e-invoicing that conforms to the European standard EN 16931 becomes mandatory for intra-EU cross-border B2B transactions, reported to tax authorities under new Digital Reporting Requirements (European Commission). Read at the plumbing level, that is not a VAT rule. It is a mass migration toward EN 16931 payloads moving over an AS4 server and the Peppol network. If you run B2B messaging for a company that trades across EU borders, ViDA 2030 is your architecture decision, and the national mandates arriving before it are the down payment.
The tax and compliance press has covered ViDA from the VAT-reporting angle in exhaustive detail. The infrastructure angle gets almost no attention, so start there.
The ViDA package was adopted by the Council on 11 March 2025, published in the Official Journal on 25 March 2025, and entered into force on 14 April 2025, with measures rolling out in stages through January 2035 (European Commission). Two dates matter for anyone who owns integration.
First, on entry into force, Member States gained the right to mandate domestic e-invoicing without asking Brussels for a derogation, and without needing the buyer’s consent for the European format (Sovos). That single change is what unlocked the national mandate wave now hitting in 2026 and 2027.
Second, from 1 July 2030, cross-border intra-EU B2B invoices must be issued as structured e-invoices conforming to EN 16931, within ten days of the chargeable event, with the data reported to the local tax authority in near real time. These Digital Reporting Requirements replace today’s recapitulative statements. By 1 January 2035, Member States that run their own domestic real-time reporting systems have to align them with the EU model.
Notice what 2030 does and does not require. It requires an EN 16931 payload and near-real-time reporting. It does not name a single transport or a single network. That distinction is the whole game for your architecture.
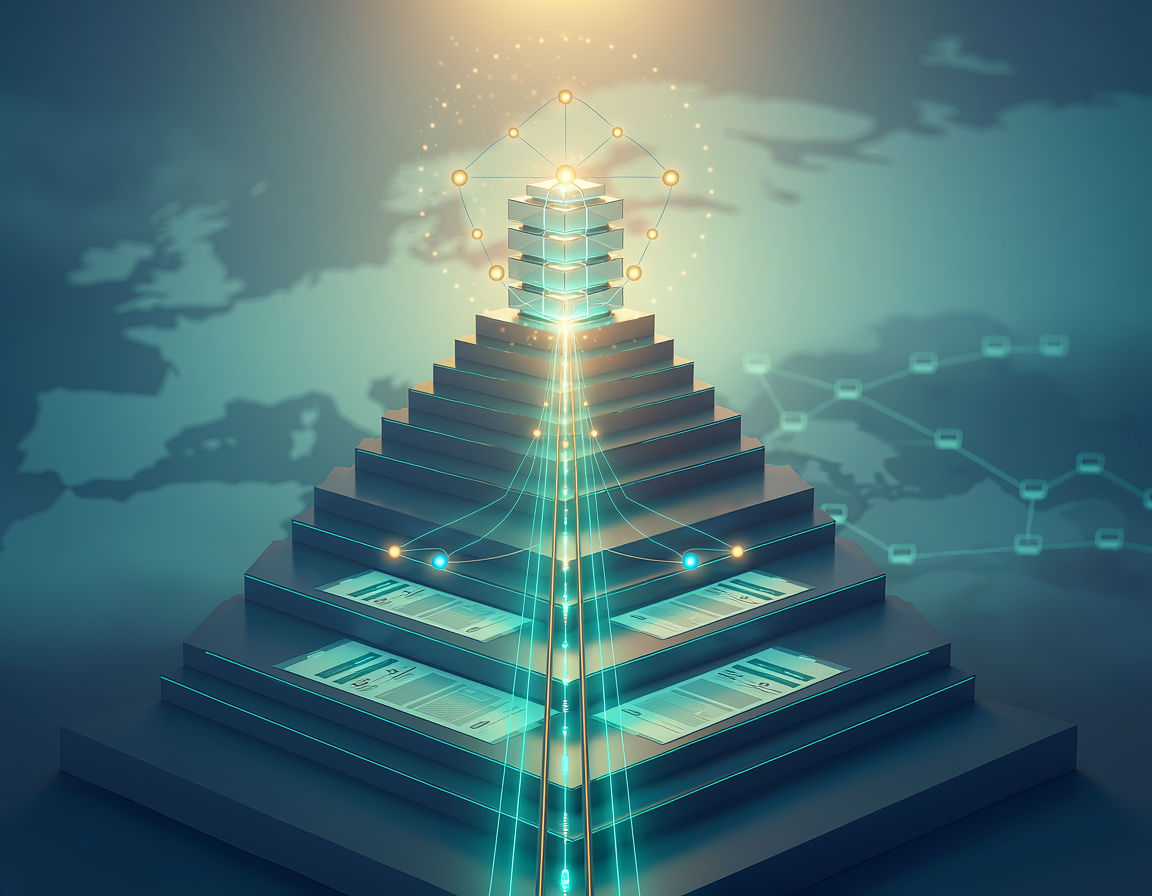
Most teams are treating Belgium, France, Poland, and Germany as four unrelated projects with four deadlines. They are not. They are steps on one staircase that ends at ViDA 2030, and every step lands on the same EN 16931 foundation.
Look at the sequence:
Belgium made structured domestic B2B e-invoicing mandatory on 1 January 2026 for Belgian-established VAT businesses, by default over the Peppol network, using Peppol BIS Billing 3.0 (a CIUS, or usage profile, of EN 16931). Alternative channels such as EDI remain permitted only where both parties agree and the same European semantic and syntax standards are met (vatcalc). The tolerance period ended on 31 March 2026 and progressive penalties now apply (Peppol Validator).
Poland switched on KSeF, its national clearance platform, on 1 February 2026 for large taxpayers (turnover above PLN 200 million) and on 1 April 2026 for most other VAT-registered businesses, with micro-entrepreneurs following on 1 January 2027 (Billed).
France begins its phased mandate on 1 September 2026: every business must be able to receive e-invoices, and large and mid-sized companies must issue them, with SMEs and micro-enterprises following on 1 September 2027 (KPMG). France runs a five-corner model through accredited platforms, the Plateformes Agréées (PA), the designation that officially replaced the earlier PDP term in the 2025 specification revisions (OpenText).
Germany has required all domestic businesses to be able to receive e-invoices since 1 January 2025, with issuing obligations phasing in on 1 January 2027 (previous year’s turnover above €800,000) and 1 January 2028 (everyone), using EN 16931-conformant formats such as XRechnung and ZUGFeRD (Novutech).
Different platforms, different corner models, different go-live dates. One shared semantic standard underneath: EN 16931. That is the pattern the VAT-angle coverage misses. If you build for each mandate as an isolated point solution, you will build the same EN 16931 mapping four times and then a fifth time for the 2030 cross-border rule. If you build for the standard once, each national mandate becomes a configuration change, not a project.
Here is the trap, stated plainly. A company facing the France 2026 deadline hires a French provider, ships a France-only integration, and moves on. Then Belgium. Then Germany’s 2027 issuing date. Then the 2030 cross-border rule arrives and none of those point solutions speak to it, so the whole thing is rebuilt. Country-by-country point solutions built for the 2026 and 2027 mandates carry a second integration bill that comes due in 2030, because none of them were designed for the cross-border reporting flow.
The build-once alternative treats EN 16931 as the internal contract. Your ERP produces one canonical structured invoice model. A messaging layer adapts that model to each destination: Peppol BIS for the decentralized-network countries, the national schema for clearance platforms, the reporting feed for the tax authority. When a new mandate lands, you add an adapter and a route. You do not touch the core.
This is an architecture argument, not a vendor pitch, and it holds regardless of who you buy from. The question to ask of any 2026 project is simple: when 2030 arrives, is this a config change or a rebuild? If the answer is rebuild, you are paying twice.
For the countries that chose the decentralized, four-corner model, the common rail is already visible, and it runs on AS4.
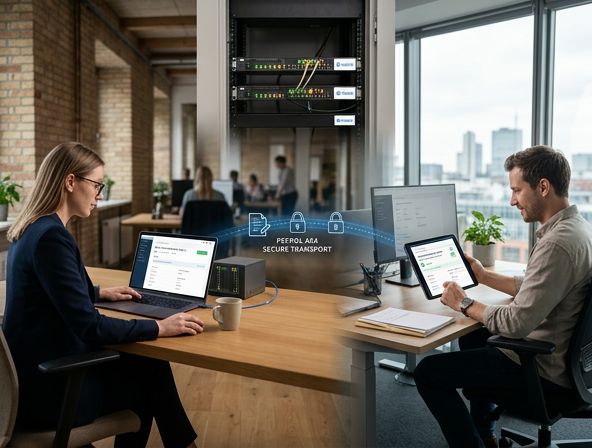
Peppol e-invoicing is the exchange of structured UBL 2.1 XML invoices, conforming to Peppol BIS Billing 3.0 and the EN 16931 model, between certified Access Points (Peppol Validator). The sender hands the invoice to its Access Point, discovery happens through the SML and SMP lookup services, and the document travels to the receiver’s Access Point over the AS4 protocol. A Peppol Access Point is, at the transport layer, an AS4 server sitting at the edge of your network. The useful way to hold the two ideas apart: EN 16931 defines what the invoice contains, and the AS4 communication protocol defines how it gets there.
That “connect once, reach everyone” property is why Peppol became the default for most European mandates, and why AS4 connectivity is the through-line from Belgium’s 2026 mandate to ViDA’s 2030 cross-border rule. The same AS4 server that carries a Peppol invoice today is the natural endpoint for the intra-EU digital reporting flow tomorrow. Aayu covers the mechanics of this network in more depth in the AS4 and eDelivery use-cases guide.
Now the honest exceptions, because pretending AS4 and Peppol cover everything would be wrong. Several large markets run centralized clearance platforms that predate or sit outside Peppol: Italy’s SDI with its FatturaPA format, Poland’s KSeF, and Romania’s e-Factura. Peppol alone does not reach these; each still needs its own integration. Germany, for its part, mandates the EN 16931 format but accepts Peppol delivery without requiring it. So the accurate picture is: AS4 and Peppol are the common rail for the decentralized-model countries and for the 2030 cross-border flow, while clearance-model countries remain separate spurs off the same EN 16931 mainline. An architecture that standardizes EN 16931 internally can serve both. An architecture built around one country’s platform cannot.
You do not need to solve 2030 in 2026. You need to make 2026 decisions that 2030 will thank you for. Five of them.
Make EN 16931 your internal invoice contract. Whatever your ERP emits, normalize it to the EN 16931 semantic model early, so every downstream route maps from one canonical source rather than from raw ERP output.
Treat the Access Point as infrastructure, not a per-country add-on. A conformant AS4 server that speaks the Peppol profile covers the decentralized mandates and positions you for the 2030 cross-border reporting flow on the same rail. For a feature-level evaluation of candidate servers, work through the AS4 software checklist for 2026.
Isolate the clearance-model countries as adapters. Italy, Poland, and Romania need their national schemas. Build those as replaceable adapters off the EN 16931 core, not as forks of it.
Keep signed receipts and audit trails from day one. ViDA reporting and every national mandate are, at heart, evidence regimes. AS4’s built-in signed receipts and non-repudiation are compliance features, not conveniences.
Choose commitment over point purchases. The teams that will spend the least across this decade are the ones treating 2026 through 2030 as a single program with one standard, not five procurements. Ask whether each purchase is a step on the staircase or a dead end.
ViDA does not force you to rebuild your B2B messaging. Building country by country does. The 2030 date is far enough away to plan for and close enough that the 2026 mandates are already writing the first check. Whether you have to write a second one in 2030 is decided now, by whether you standardize on EN 16931 and put a conformant AS4 server on the rail, or keep solving one country at a time.
For a fuller map of where AS4 is already mandated and where it is heading, see Is AS4 mandatory? Understanding global compliance requirements.
No. ViDA requires structured e-invoices that conform to EN 16931 and near-real-time digital reporting for intra-EU cross-border B2B from 1 July 2030. It does not name a transport network. Peppol, which uses the AS4 protocol between Access Points, is the de facto rail for the decentralized-model countries, but clearance-model states such as Italy and Poland use their own national platforms.
1 July 2030 for intra-EU cross-border B2B transactions. The package was adopted on 11 March 2025 and entered into force on 14 April 2025, with a further alignment deadline of 1 January 2035 for countries that run their own domestic real-time reporting systems.
EN 16931 is the European semantic standard that defines the core data an e-invoice must contain. Every national mandate (Belgium, France, Germany and others) and the 2030 cross-border rule build on it. Making EN 16931 your internal invoice contract lets each mandate become a routing change rather than a fresh integration.
Under the Peppol four-corner model, invoices travel between certified Access Points over the AS4 communication protocol. A Peppol Access Point is an AS4 server at the network edge. The same AS4 connectivity that carries Peppol invoices today is the natural endpoint for ViDA’s 2030 cross-border reporting flow.
Because a France-only point solution does not speak to Belgium, Germany’s 2027 issuing rule, or the 2030 cross-border mandate. A country-by-country build means paying for a second integration wave when 2030 arrives. Standardizing on EN 16931 now turns each later deadline into a configuration change.
Every mandate on the staircase, from Belgium’s live penalty regime to France’s September 2026 receive-all rule to ViDA’s 2030 cross-border flow, lands on the same two decisions: an EN 16931 core and a conformant AS4 Access Point.
Configure a real trading partner connection and run a live EN 16931 flow end to end before your next mandate deadline. Prefer a guided walkthrough against your specific partner profile? Book a 30-minute technical demo with our integration team.
Join hundreds of organizations already taking full control of their B2B AS2 communications with our trusted solutions. Contact us today to tailor a solution that fits your specific AS2 EDI needs.
Get full access to whichever product fits your needs. Configure real trading partner connections, run end-to-end transactions, and see the platform perform before making any commitment. All three products include a free 30-day trial with no restrictions.


